Buying a home here is one of the biggest money decisions you’ll ever make. Your broker sits right in the middle of it. First phone call, mountains of paperwork, closing day, the keys in your hand – they touch all of it. Pick a good one and closing feels almost boring, in the best way. Pick the wrong one and you’ll spend weeks chasing down documents nobody warned you about.
That’s the whole reason to slow down before you sign with anybody. A solid mortgage broker in South Carolina gives you more than a list of loan options. They listen. They keep track of your deadlines. And they know the local ground well enough to see problems coming before those problems land on you.
Here’s what actually matters when figuring out how to choose a mortgage broker – the qualifications, the questions to ask, and a few South Carolina quirks that can quietly move your numbers. And when you’re ready, we’re here to help at BrickWood Mortgage because we think we tick all the boxes!
Key Qualifications to Look For
Does the Broker Hold a Valid South Carolina Mortgage License?
Start here. Every time. Before you sink an hour into a conversation, make sure the broker is licensed to work in South Carolina. That license means they’ve cleared the state’s standards and passed the education and testing. Look it up yourself on the Nationwide Multistate Licensing System (NMLS). Takes two minutes. Then you know you’re dealing with somebody legit.
How Much Local Market Experience Does the Broker Have?
Years in the business? Nice. Years in this market matter more. A broker who knows the neighborhoods, the property values, how lending tends to shake out around here – that person tends to land better results for clients. Somebody who’s closed deals in Charleston, Columbia, or Greenville will catch things an out-of-state broker breezes right past.
What Certifications and Memberships Does the Broker Hold?
Credentials say something. So does belonging to a group like the South Carolina Mortgage Bankers Association. Both hint at a broker who takes the education and the ethics seriously. Ask. Usually it points to someone keeping up with rule changes instead of running on what they learned a decade back.
What Do Past Clients Say About the Broker?
Read the reviews. Slowly. How did they handle the hard files? Did they keep you in the loop when things got messy? Did they actually do what they promised? A record like that tells you far more than some tidy tagline stuck at the top of a website. It’s also one of the clearest benefits of using a mortgage broker – you get someone with a track record you can actually check.
Questions to Ask Potential Brokers
Which Lenders Does the Broker Work With?
Networks aren’t equal, not even close. Ask flat out – can they shop your loan across a bunch of lenders for competitive rates, or are they boxed into a handful? Wider access usually means more negotiating muscle on your side.
How Is the Broker Compensated?
Fee surprises love a bad moment. Get the money question out of the way early. Whether the broker gets paid by the lender or by you, a trustworthy one gives you a straight answer and doesn’t dodge.
How Will the Broker Guide You Through the Process?
First time through, the paperwork feels like a lot. You want somebody who’ll walk you stage by stage, pre-approval clear through to closing, so nothing knocks you sideways halfway in. Ask how hands-on they plan to be. Then hold them to it.
What Is the Broker’s Average Time to Close?
Timelines swing. And delays pile on pressure, especially with a purchase contract deadline breathing down your neck. These are exactly the kinds of questions to ask mortgage broker candidates early – their average time to close, and how they handle the snags too – appraisal issues, an underwriting holdup – and how they handle those.
Local South Carolina Considerations
Does the Broker Understand SC-Specific Lending Requirements?
South Carolina has its own lending requirements and property regulations. They can shape your loan in ways you’d never see coming. A sharp broker stays current, so you’re not scrambling at the last minute.
Is the Broker Familiar with Local Market Trends?
Conditions shift from one corner of the state to another. Myrtle Beach on the coast moves to a different beat than somewhere inland like Spartanburg. A broker with real local insight sets honest expectations on pricing and negotiation. Not guesses.
Does the Broker Understand South Carolina Homeowner Insurance Requirements?
Insurance rules here – flood-prone areas, coastal spots especially – can push your monthly payment past what you’d planned for. A broker who brings this up early saves you a nasty budget scramble right before closing.
Does the Broker Have Strong Local Connections?
Good relationships with local appraisers, inspectors, and title companies keep things moving. Fewer snags. Less friction. A smoother run through underwriting and closing.
Frequently Asked Questions
How long does it typically take to close on a mortgage in South Carolina?
Most closings land in the 30 to 45 day range. It can stretch depending on your loan type, how backed up the lender is, and whatever odd thing turns up during underwriting.
Do I need a mortgage broker if I’m already working with a specific lender?
Not necessarily. Still, a broker can open the door to several lenders and loan products – often more choices and better rates than going it alone with one lender.
What’s the difference between a mortgage broker and a loan officer?
A mortgage broker works across several lenders to match you with the right loan. A loan officer usually represents just one institution.
Finding the Right Partner for Your Home Purchase
When it’s all said and done, it comes down to trust, transparency, and local know-how. The right broker feels like a partner in your homebuying journey, not another vendor waiting to cash a check. When you’re ready to start talking, find someone who answers you straight and helps you land the mortgage that actually fits your life. We’re experienced, friendly, and ready to help at BrickWood Mortgage!
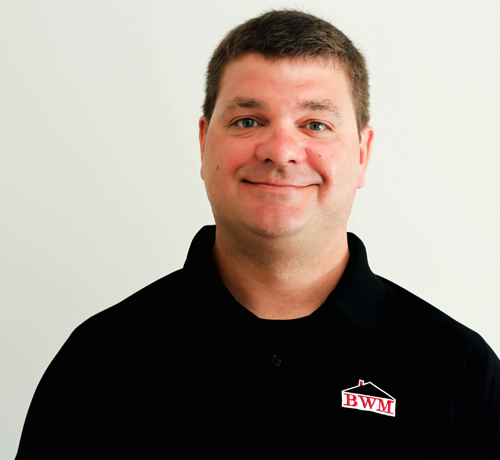
Paul Hankins, founder of Brickwood Mortgage, is a South Carolina native, entrepreneur, and seasoned mortgage professional with more than 23 years of experience in residential lending, real estate investment, property management, and renovation projects in South Carolina.

 © 2007-2026 BrickWood Mortgage Inc. All Rights Reserved.