Buying on the Grand Strand? Here’s when your lender needs flood insurance, how to check the map, and the local discounts most buyers don’t know about.
 Paul Hankins
Founder & Broker · NMLS #281393
If you’re buying in Myrtle Beach or anywhere on the Grand Strand, your lender will require flood insurance when the home sits in a high-risk flood zone. That’s any FEMA zone starting with A or V. The rule applies to most home loans, including conventional, FHA and VA loans and loans from federally regulated banks. It also applies in a few protected coastal barrier areas. Outside those areas, flood insurance is usually your choice.
Myrtle Beach flood zone map: how to look up a house
Type the address into FEMA’s flood map. Horry County also posts its FEMA flood maps on the county site. The maps in effect for Myrtle Beach, North Myrtle Beach, Surfside Beach, Conway and the rest of Horry County date from December 16, 2021. In Georgetown County, the Town of Pawleys Island’s map dates from May 9, 2023. The map for the rest of the county, outside the City of Georgetown, dates from June 18, 2025.
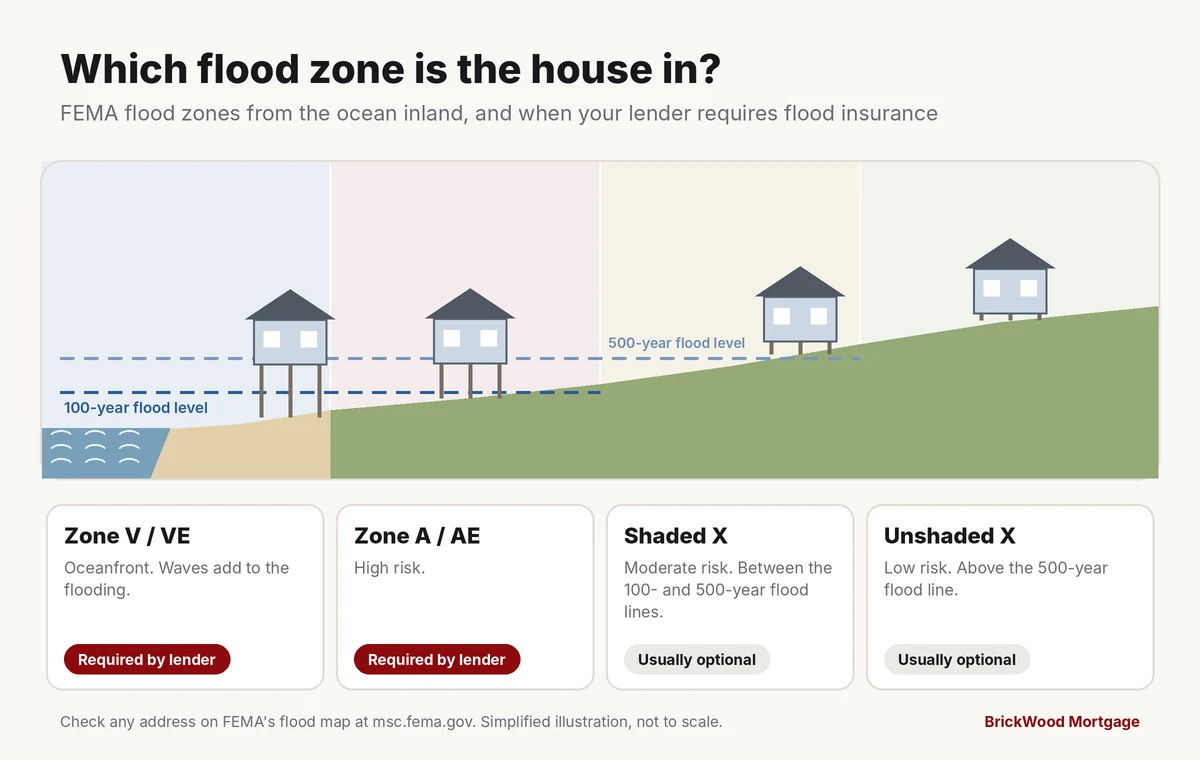
Every home on the map is in some flood zone. The question is whether your zone makes flood insurance a requirement for your loan. Here is what the letters mean:
| Zone | What it means | Required for your loan? |
|---|---|---|
| Starts with A (like AE) | High risk. | Yes |
| Starts with V (like VE) | High risk on the oceanfront, where waves add to the flooding. | Yes |
| Shaded X (called B on older maps) | Moderate risk. Usually between the 100-year and 500-year flood lines, or shallow flooding, usually under a foot deep. | Usually not, but you can still buy it |
| Unshaded X (called C on older maps) | Low risk. Usually above the 500-year flood line. | Usually not, but you can still buy it |
Once you’re under contract and apply, the lender orders a flood certificate (often called a flood cert) on the home. It’s a standard FEMA form that shows which flood zone the house is in on FEMA’s map. If the home is in a high-risk zone, you’ll get a written notice before closing. A shed, or a detached garage with no living space, in the zone doesn’t trigger the rule when the house itself is outside it.
Some Grand Strand communities get a discount on flood insurance
Here’s a local detail that can save you money. Several Grand Strand communities take extra flood-safety steps through FEMA’s Community Rating System, and in return federal flood policies there cost less. The discount depends on where the home is:
| Community | High-risk zone discount | Other zones |
|---|---|---|
| City of Myrtle Beach | 25% | 10% |
| Unincorporated Horry County (like Carolina Forest, Socastee and Garden City) | 25% | 10% |
| Town of Pawleys Island | 25% | 10% |
| City of North Myrtle Beach | 20% | 10% |
| Town of Surfside Beach | 15% | 5% |
| Unincorporated Georgetown County (like Murrells Inlet) and the City of Georgetown | 15% | 5% |
| Conway, Loris, Aynor, Atlantic Beach, Briarcliffe Acres | None | None |
These discounts apply to policies through FEMA’s National Flood Insurance Program, and they follow town limits, not mailing addresses. Ask your insurance agent to confirm it’s on your quote.
Is flood insurance required in Zone X?
Usually not. Federal rules don’t require it in shaded or unshaded Zone X, unless the home is in one of the protected coastal barrier areas. But Zone X isn’t “no risk”, and homes there can flood, for example from heavy rain that collects or drains poorly. FEMA recommends flood insurance there. Most homeowners insurance doesn’t cover flooding, so you need a separate flood policy to be covered. In the City of Myrtle Beach, a federal flood policy on a Zone X home also gets the 10% discount above.
How much flood insurance does the lender require?
The lender needs coverage on the building equal to the lowest of these three amounts:
- what it would cost to rebuild the house;
- $250,000, the most a standard federal flood policy covers on a house;
- your loan amount.
Coverage for your furniture and belongings is usually your choice. The required coverage is on the house, not the land under it.
How much is flood insurance in Myrtle Beach?
There’s no one number. Federal flood policies are priced home by home, based on how high the house sits, how close it is to water and what it would cost to rebuild. Two houses on the same street can have very different bills. Get a quote on the house you want before you make an offer.
The premium then becomes part of your monthly housing cost, just like taxes and homeowners insurance. Lenders compare that total with your income, so a high flood premium can lower the price you qualify for.
An example. Two Horry County houses have the same price. One is in Zone X. The other sits in an AE zone near the marsh. The AE house needs a flood policy, and that premium is added to the monthly cost. With the same income, the buyer qualifies for a little less on the AE house.
A few more things to know:
- It’s usually paid through escrow. Regulated lenders generally collect the premium with your monthly payment.
- No waiting period when you buy. A federal flood policy bought with your new loan starts at closing, as long as you apply and pay by closing. Without a loan, a new policy normally waits 30 days.
- Private flood insurance works too. Lenders accept private policies that give at least the same coverage as a federal policy.
Can an elevation certificate lower your flood insurance?
It can. An elevation certificate is a form a surveyor fills out showing how high the house sits compared with the flood level on the map. FEMA no longer requires one to buy a federal flood policy. It estimates each home’s height from its own data. But if the house sits higher than FEMA’s estimate, giving the certificate to your insurance agent may lower your premium.
Ask the seller early whether they have one. If not, your insurance agent can tell you whether paying a surveyor for one is likely to help on that house.
Can a house be taken out of a flood zone?
Sometimes. If the ground right next to the house is higher than the flood level on the map, the owner can ask FEMA for a Letter of Map Amendment, called a LOMA. If FEMA agrees, the lender no longer requires flood insurance on that house. If the home you’re buying already has one, ask the seller for a copy.
Buying a condo in a flood zone?
For an oceanfront or marsh-side condo in a high-risk zone, the lender looks for a master flood policy the HOA carries on the building. If the HOA’s coverage for your unit falls short of what your loan needs, you buy a policy of your own to fill the gap. More in our guide to Myrtle Beach condo financing.
We help buyers across the coast, from North Myrtle Beach and Myrtle Beach to Pawleys Island.
Buying near the water on the Grand Strand?
Talk with a BrickWood loan officer about how flood insurance fits your budget, and get pre-qualified before you shop.
Flood insurance questions
Do I need flood insurance in Myrtle Beach?
Only if the home is in a high-risk FEMA flood zone, one starting with A or V, or in a protected coastal barrier area. Then your lender requires it. In shaded or unshaded Zone X, outside those coastal barrier areas, it’s usually your choice, though homes there can still flood.
Is flood insurance cheaper in Myrtle Beach?
Federal flood policies in the City of Myrtle Beach get a 25% discount in high-risk zones and 10% elsewhere, through FEMA’s Community Rating System. The City of North Myrtle Beach gets 20% and 10%, and the Town of Surfside Beach 15% and 5%.
Is flood insurance required to be escrowed?
Usually. Federally regulated lenders must collect flood premiums through escrow, with a few exceptions, so the premium is paid along with your monthly mortgage payment.
Is there a waiting period for flood insurance when buying a house?
No. A federal flood policy bought with a new loan takes effect at closing, as long as you apply and pay by then. Without a loan, a new policy normally starts 30 days after you apply and pay.
What is a flood certificate?
A flood certificate, or flood cert, is a standard FEMA form the lender uses to record a home’s FEMA flood zone. The lender orders it after you apply. If the home is in a high-risk zone, flood insurance becomes a requirement of the loan.
About Paul Hankins
Paul founded BrickWood Mortgage in 2007 and has spent more than 20 years in residential lending. In 2025 the Governor appointed him to the South Carolina Council of Advisors on Consumer Credit.
Sources
- FEMA OpenFEMA, NFIP Community Status Book (South Carolina)
- Horry County, FEMA Flood Maps
- 12 CFR Part 339, Loans in Areas Having Special Flood Hazards
- Fannie Mae Selling Guide B7-3-06, Flood Insurance Requirements
- 44 CFR Part 61, NFIP coverage
- FloodSmart (FEMA), what affects your premium
- FEMA Flood Map Service Center
- FloodSmart (FEMA), what is my flood zone
- FloodSmart for agents, Risk Rating 2.0 and elevation certificates
Disclaimer. This article is provided for general educational purposes only and is not an offer or commitment to lend. Not all loan programs mentioned, including down payment assistance and third-party or government programs, are offered by BrickWood Mortgage Inc. Program availability, terms and eligibility vary by lender and location and are subject to change. Please contact a licensed loan officer to find out which programs we currently offer.
This material is not provided by, endorsed by, or approved by HUD, FHA, VA, or any government agency.
 Equal Housing Lender. We do business in accordance with the Fair Housing Act and the Equal Credit Opportunity Act.
BrickWood Mortgage Inc. NMLS #189497. 1601 Glenns Bay Rd., Surfside Beach, SC 29575. (843) 314-4101.
Paul Hankins, founder of Brickwood Mortgage, is a South Carolina native, entrepreneur, and seasoned mortgage professional with more than 20 years of experience in residential lending, real estate investment, property management, and renovation projects in South Carolina.

 © 2007-2026 Brickwood Mortgage Inc. All Rights Reserved.