Oceanfront tower, resort building or a small complex off the beach? Here’s how condo loans work on the Grand Strand now.
 Paul Hankins
Founder & Broker · NMLS #281393
Financing a condo in Myrtle Beach comes down to two questions: do you qualify, and does the building? In 2026, Fannie Mae changed the rules for the building part. For the oceanfront towers and resort-style buildings along the Grand Strand, some of those changes help and some hurt. Here’s what changed and what it means if you’re buying.
What changed for condo loans in 2026
1. The quick building check is gone. Lenders used to be able to approve many condo buildings with a short checklist, called a Limited Review. For loan applications dated on or after August 3, 2026, that option is gone. A finished building with more than 10 units, which covers most oceanfront towers, now needs a full review of its budget, savings, repairs and insurance, FHA approval, or a review by Fannie Mae itself.
2. The 50% investor limit is gone, for finished buildings. Fannie Mae used to require that at least half the units in a building be owned by people who live there or use them as second homes, before it would back a loan on a rental unit. That rule is gone for established buildings. That’s good news on the Grand Strand, where many buildings are full of rentals. A building can still fail if it runs like a hotel. A brand-new building still needs at least half its units sold to people who will live there or use them as second homes.
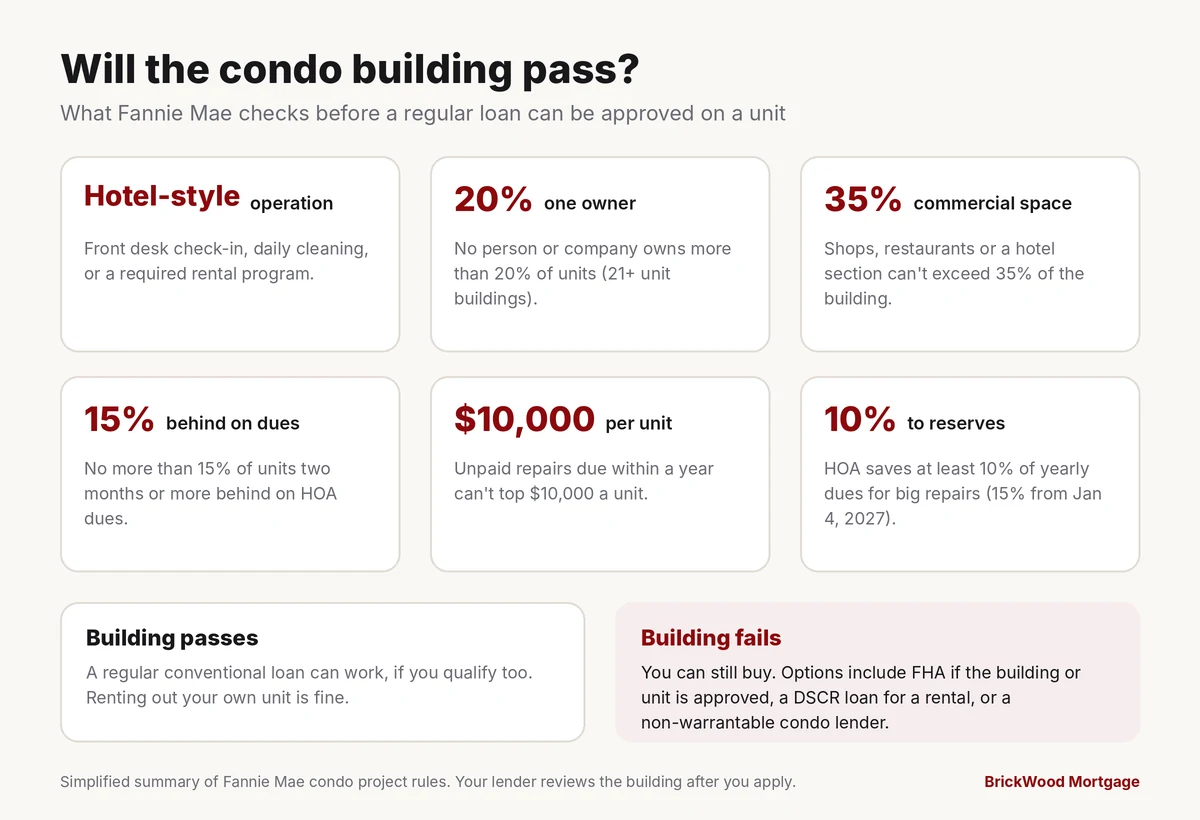
3. HOAs must save more. The HOA has to put at least 10% of the dues it collects each year into savings for big repairs. For loan applications dated on or after January 4, 2027, that rises to 15%.
Small buildings are simpler. Buildings of two to four units skip the full review, and so do five- to ten-unit buildings that aren’t part of a bigger complex.
Condo-hotels and buildings with a front desk
This is the big one at the beach. Fannie Mae won’t back a loan on a unit in a building that operates like a hotel, even though each unit has its own owner. Signs a Myrtle Beach building may be treated as a hotel:
- a front desk that checks in guests, or daily cleaning service;
- a rule that owners must put their unit in the rental program;
- owners must split rental income with the HOA or a rental company;
- “hotel” or “resort” in its name, or marketing as a hotel or investment.
Renting out your own unit is fine. It’s the building’s setup that matters.
Other reasons a condo can’t get a regular loan
A building that fails Fannie Mae’s rules is called non-warrantable. Besides hotel-style operations, the usual reasons are:
- Big repairs with no money set aside. Problems like a failing sea wall, leaks, or a failed structural inspection, or more than $10,000 a unit of unpaid repairs due within a year.
- A special assessment for those repairs. If the extra bill pays for a serious repair that isn’t fixed yet, the building can’t pass.
- One owner has too many units. In a building of 21 or more units, no single person or company can own more than 20% of them.
- Too much commercial space. Shops, restaurants or a hotel section can’t take up more than 35% of the building.
- Owners behind on dues. No more than 15% of units can be two months or more behind on HOA dues.
If the condo doesn’t qualify
You can still buy it. A non-warrantable condo just needs a different kind of loan. BrickWood is a mortgage broker, so we can take your loan to lenders that make condo loans outside Fannie Mae’s rules. The terms are different from a regular loan, and your loan officer will walk you through them.
- FHA: works if the building is FHA-approved, or if the single unit can get FHA approval on its own. See our FHA loans.
- DSCR: buying it as a rental? A DSCR loan qualifies you on the rent.
Renting out your Myrtle Beach condo
Many buyers plan to rent their unit some weeks. A few local things to budget for:
- Lodging taxes. A short-term rental inside the City of Myrtle Beach collects about 13% in lodging taxes on each stay. For lodging taxes, South Carolina counts any stay under 90 days in a row as short-term.
- North Myrtle Beach. The city requires a business license to rent short-term. For now there is no separate rental permit.
- How you’ll use it changes the loan. If you’ll stay there part of the year and keep control of the bookings, it can be a second home.
Insurance on a beach condo
If the building sits in a high-risk flood zone, the lender looks for a master flood policy the HOA carries on the building. Myrtle Beach and North Myrtle Beach get discounts on federal flood insurance; see flood insurance in Myrtle Beach.
Tips before you make an offer
- Ask the listing agent whether recent buyers in the building used regular loans. It’s a quick hint about whether the building passes.
- Ask about special assessments and planned repairs.
- Check whether the building has a front desk or a required rental program.
- Get pre-qualified, and tell your loan officer it’s a condo. Once you’re under contract and apply, the lender reviews the building.
We help condo buyers in Myrtle Beach, North Myrtle Beach, Litchfield and across the Grand Strand.
Shopping for a Myrtle Beach condo?
Get pre-qualified with BrickWood. We work with lenders for both regular and non-warrantable condos, so you have options either way.
Condo loan questions
Can you finance a condo-hotel in Myrtle Beach?
Not with a regular Fannie Mae loan, because Fannie Mae won’t back a loan in a building that runs like a hotel. You can still finance one with a non-warrantable condo loan from a lender that lends outside Fannie Mae’s rules.
What is a non-warrantable condo?
A non-warrantable condo is a unit in a building that doesn’t meet Fannie Mae’s rules, so it can’t get a regular conventional loan sold to Fannie Mae. Common reasons are hotel-style operations, big unfunded repairs, one owner with too many units, or too much commercial space.
Did Fannie Mae get rid of Limited Review for condos?
Yes. Fannie Mae retired Limited Review for loan applications dated on or after August 3, 2026. Established buildings with more than 10 units now need a full review, FHA approval or a Fannie Mae review.
Can I rent out my Myrtle Beach condo and still get a regular mortgage?
Yes, if the building qualifies. Renting your own unit is fine. In the City of Myrtle Beach, short-term stays collect about 13% in lodging taxes, so build that into your plans.
About Paul Hankins
Paul founded BrickWood Mortgage in 2007 and has spent more than 20 years in residential lending. In 2025 the Governor appointed him to the South Carolina Council of Advisors on Consumer Credit.
Sources
Disclaimer. This article is provided for general educational purposes only and is not an offer or commitment to lend. Not all loan programs mentioned, including down payment assistance and third-party or government programs, are offered by BrickWood Mortgage Inc. Program availability, terms and eligibility vary by lender and location and are subject to change. Please contact a licensed loan officer to find out which programs we currently offer.
This material is not provided by, endorsed by, or approved by HUD, FHA, VA, or any government agency.
 Equal Housing Lender. We do business in accordance with the Fair Housing Act and the Equal Credit Opportunity Act.
BrickWood Mortgage Inc. NMLS #189497. 1601 Glenns Bay Rd., Surfside Beach, SC 29575. (843) 314-4101.
Paul Hankins, founder of Brickwood Mortgage, is a South Carolina native, entrepreneur, and seasoned mortgage professional with more than 20 years of experience in residential lending, real estate investment, property management, and renovation projects in South Carolina.

 © 2007-2026 Brickwood Mortgage Inc. All Rights Reserved.